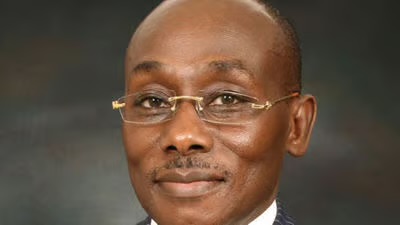
The sale of Peter Wambua Muthoka’s airport cargo business to Turkish aviation giant Çelebi has turned a long-running Kenyan corporate saga into a multibillion-shilling exit.
Çelebi Cargo GmbH completed the acquisition of 100 percent of Transglobal Cargo Centre Ltd, which operates under the Africa Flight Services brand at Jomo Kenyatta International Airport, on December 23, 2025 for US$40.1 million, about Sh5.2 billion at the exchange rates used in recent reports.
Çelebi’s financial statements show why the transaction has attracted fresh attention. Transglobal’s tangible assets were valued at about 833.2 million Turkish lira on the acquisition date, while the total consideration was approximately 1.63 billion lira.
The resulting 798.9 million lira was recognised as goodwill, representing the premium paid above the identifiable tangible assets. Business Daily calculated the premium at roughly Sh2.5 billion, or about US$19.6 million.
That is the clean financial story.
The less tidy story goes back more than a decade, to a lease on Kenya Airports Authority land, a Sh510 million Standard Chartered facility, questions raised by KAA lawyers and parliamentary scrutiny over how the arrangement was structured.
The Sh510 million loan that put KAA land under the spotlight
In April 2010, Transglobal obtained a Sh510 million loan from Standard Chartered Bank.
The financing became controversial because it was connected to Transglobal’s leasehold interest at JKIA, land owned by KAA.
Contemporary reporting showed that the lease had an initial 20-year term beginning October 1, 2008, with an automatic additional 20 years and a further 20 years available to the tenant, potentially taking the arrangement to 60 years.
KAA’s lawyers, Albert Mumma and Company Advocates, raised questions about the security arrangement, saying the charge documents did not provide the Authority with sufficient information about the loan period, repayment terms and drawdown conditions.
The lawyers also questioned KAA’s position if Transglobal ran into financial difficulties, warning that the Authority appeared to have limited control over a long-term interest in its own land.
More significantly, the legal opinion questioned whether KAA had sufficient control over a future transfer of Transglobal’s shares and whether the Authority would necessarily acquire the fixtures, plant and equipment that formed the core of the cargo-handling operation at the end of the arrangement.
The issue eventually reached Parliament.
The Public Investments Committee questioned how the arrangement had been structured and why a 20-year lease had apparently evolved into a potential 60-year interest. Contemporary reports said the committee wanted explanations from Treasury, the National Land Commission and Standard Chartered.
But there was an important counterpoint.
In 2013, then acting KAA managing director Lucy Mbugua told Parliament that Transglobal had not charged KAA’s land itself. She said the security related to the company’s leasehold interest and business assets rather than ownership of the airport land.
That distinction matters.
There is no evidence that Muthoka acquired ownership of the JKIA land. The documented controversy concerned the value and security attached to Transglobal’s leasehold interest and the corporate assets operating from the airport.
In other words, the public land remained public.
The commercial value generated from the airport concession, however, remained private.
Then came the Sh5.2 billion exit
Fast-forward to December 2025.
Çelebi Cargo GmbH, the Frankfurt-based subsidiary of Çelebi Aviation, acquired all the shares held by Transglobal’s principal shareholder for US$40.1 million.
Çelebi said the transaction was part of its international expansion and would give it an entry into Kenya’s aviation services market.
The Competition Authority of Kenya approved the acquisition unconditionally in January 2026, saying the deal was unlikely to harm competition in the Kenyan cargo-handling market or raise negative public-interest concerns.
That approval is significant because it establishes what the current regulatory record actually says: the takeover itself was cleared by Kenya’s competition regulator.
It does not, however, erase the historical questions surrounding the way Transglobal’s airport interests were structured more than a decade earlier.
Those are separate issues.
Transglobal was no ordinary airport business
The company being sold had built a substantial position at JKIA.
Transglobal trades as Africa Flight Services, providing ground handling, air-cargo and warehousing services.
KAA data cited in recent reports put AFS at about 33 percent of JKIA export cargo, ahead of Kenya Airways Cargo at 22 percent. On imports, AFS handled about 20 percent compared with KQ Cargo’s 32 percent.
Çelebi says its Kenyan operation now operates a 12,350-square-metre warehouse, including 3,300 square metres of temperature-controlled storage, with an annual cargo-handling capacity of 275,000 tonnes.
That explains part of the premium.
Çelebi was not simply buying buildings and equipment. It was buying an established operating business at one of Kenya’s most strategically important airports, including its customer relationships, licences, workforce, infrastructure and position in the cargo market.
The Sh2.5 billion goodwill figure therefore should not be described as money paid for KAA land.
It was the accounting premium attached to the acquired business.
The CMC Holdings chapter
Transglobal is not Muthoka’s first major corporate exit.
In 2014, Dubai-based Al-Futtaim acquired CMC Holdings in a deal that valued the motor dealer at about Sh7.5 billion. Muthoka, then the largest shareholder, received approximately Sh1.8 billion for his 24.7 percent stake.
But the CMC story was preceded by a bitter corporate-governance battle.
Muthoka had served as chairman of CMC while also being associated with Andy Forwarders, a logistics company that supplied CMC.
A subsequent PwC forensic review became central to the dispute. Reports around the controversy said Andy Forwarders had allegedly overcharged CMC, with PwC putting the disputed amount at about Sh1.1 billion. Earlier estimates had placed the alleged overcharging at between Sh1.5 billion and Sh2 billion.
CMC subsequently filed a High Court suit seeking about Sh1.5 billion from Andy Forwarders and others. Court records confirm the existence and nature of that litigation.
Muthoka disputed the allegations.
The Capital Markets Authority also took regulatory action during the CMC crisis. In 2012, it imposed a lifetime disqualification on Muthoka from serving on boards of listed companies.
But that sanction did not remain lifetime.
In 2016, the CMA reviewed the decision and reduced the disqualification to five years, running from August 3, 2012 to August 3, 2017. The regulator said its decision followed petitions by Muthoka and Joseph Kivai and consideration of their submissions.
That distinction is important today.
It would be inaccurate to describe Muthoka as currently subject to a lifetime CMA ban.
The documented record shows that the original lifetime prohibition was later reduced.
A second billion-shilling exit
The figures now tell a striking story.
Muthoka’s CMC stake generated about Sh1.8 billion when Al-Futtaim acquired the company.
More than a decade later, his airport cargo business was sold for about Sh5.2 billion.
The two transactions are not evidence of wrongdoing.
They do, however, illustrate the scale of Muthoka’s corporate exits and explain why the old Transglobal file has returned to public attention following the Çelebi transaction.
The current deal has also exposed a remarkable contrast.
The airport business once sat at the centre of questions over a Sh510 million financing facility.
It has now been sold for an amount roughly ten times that original facility.
What happened to the old questions?
This is where the story becomes uncomfortable.
The Competition Authority has cleared the acquisition. Çelebi has entered Kenya legally and transparently through an approved corporate transaction. There is no evidence in the current regulatory record that the acquisition itself was improper.
But the historical questions raised by KAA’s lawyers and Parliament concern an earlier period.
Who authorised the structure of the original lease?
Why was an airport concession potentially capable of extending to 60 years?
What exactly was registered as security for the Sh510 million facility?
What approvals were obtained from KAA and other public authorities?
And what rights did KAA ultimately retain over the buildings, fixtures and equipment forming the cargo operation?
Those questions were publicly raised years before Çelebi entered the picture. Contemporary reporting recorded KAA’s lawyers questioning the absence of key financing information and the Authority’s limited control over the long-term arrangement.
The subsequent parliamentary record also shows that KAA officials disputed the characterisation that the airport land itself had been charged.
Both pieces of the record need to remain in the story.
The real asset was the operating position
There is another way to read the Sh2.5 billion goodwill figure.
The market was not necessarily putting a price on land.
It was putting a price on access.
Access to JKIA.
Access to cargo customers.
Access to established infrastructure.
Access to an operating platform handling a substantial portion of the airport’s export cargo.
And access to a business that had spent years building its position in one of the country’s most strategically important logistics hubs.
That is what Çelebi bought.
The company says its Kenyan operation is now part of its international network and intends to combine AFS’s local expertise with its global systems and infrastructure.
Muthoka, meanwhile, has said he wanted to invest in other areas. He also indicated that part of the proceeds went towards repaying debt used by Transglobal to upgrade its facilities.
He continues to operate in logistics through Acceler Global Logistics, according to Business Daily.
The unanswered ledger
The most important point is not that Muthoka sold a successful company for Sh5.2 billion.
It is that the sale has reopened an old public-asset debate.
A private company built a major cargo operation on KAA land.
Its lease was structured over decades.
Its leasehold and business interests became connected to bank financing.
KAA’s own lawyers raised concerns about the arrangement.
Parliament questioned how the lease had evolved and how the security had been created.
Years later, the company became valuable enough for a multinational aviation group to pay US$40.1 million for control.
The current sale is lawful on the regulatory record.
The old questions are different.
They concern how a public airport concession was originally structured, what protections KAA had, and whether the interests of the public landlord were adequately safeguarded.
Until those questions are answered with the underlying lease, charge documents, approvals and parliamentary records placed side by side, the Sh2.5 billion goodwill figure tells only half the story.
The other half is buried in a Sh510 million loan file that first put Peter Muthoka, Transglobal Cargo Centre and KAA’s airport land under the spotlight more than a decade ago.
There's no story that cannot be told. We cover the stories that others don't want to be told, we bring you all the news you need. If you have tips, exposes or any story you need to be told bluntly and all queries write to us [email protected] also find us on Telegram
